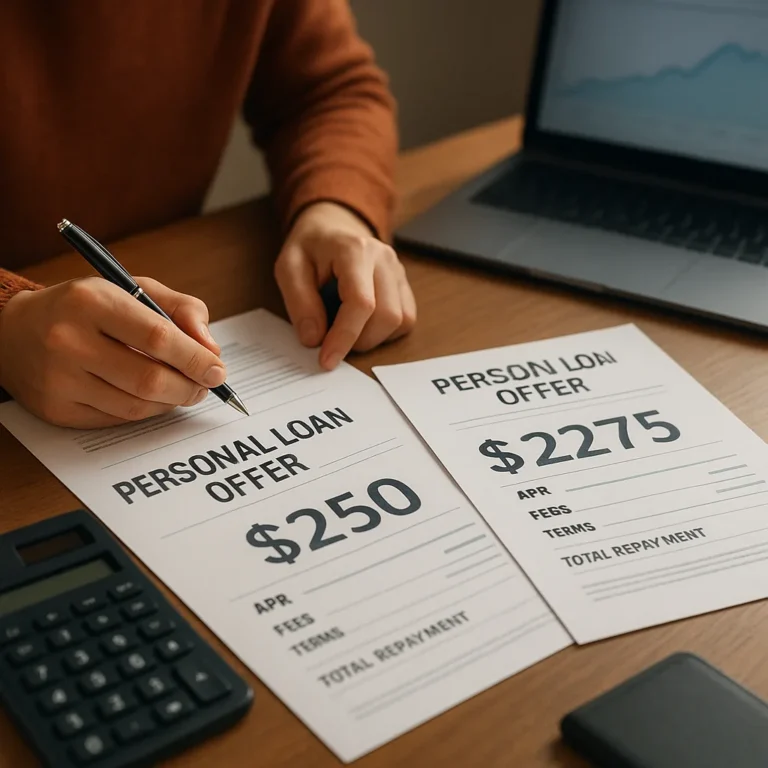
Two personal loan offers can advertise the same amount and term while producing very different bills. The monthly payment is useful for checking affordability, but it can hide origination fees, optional add-ons, a longer repayment period, or a rate that changes. A sound comparison puts every dollar and every condition in one view before you apply. Start with the loan's annual percentage rate, then examine total repayment, fee timing, collateral requirements, and consequences if your income changes. The goal is not to find the smallest payment at any cost. It is to choose borrowing that solves a defined need without creating an avoidable financial strain for your household or delaying a purchase that can wait.
Start With the APR and Total Repayment
Ask each lender for the same loan amount and repayment term so the comparison is meaningful. Then focus on the annual percentage rate, which generally reflects interest plus certain mandatory fees, rather than the interest rate alone. Request a written breakdown showing the amount deposited, finance charge, origination fee, and total of payments. A lender that quotes only a monthly figure is not giving you enough context. Use a simple worksheet with one row per offer. If the loan terms differ, calculate what each option costs over its full scheduled life before deciding whether a lower payment is worth additional interest.
Identify Fees Before Comparing Offers
Fees can change the comparison before the first payment is due. An origination fee may be deducted from the loan proceeds, meaning a $10,000 approval could deposit less than $10,000 while requiring repayment based on the stated principal. Ask whether the lender charges application, late-payment, prepayment, or returned-payment fees, and whether optional insurance is included. Do not confuse a fee waiver with a free loan; a higher rate may replace the upfront charge. Write down when each fee applies and whether it is refundable. This detail helps you compare the cash you receive with the cash you must repay.
Review the Risks Behind the Price
Risk matters as much as price, especially when a loan is secured or the rate can change. A secured loan may offer a lower rate, but missing payments could put a vehicle or other pledged asset at risk. For an unsecured loan, review what happens after a late payment, including penalty rates, collection activity, and credit reporting. Confirm whether the rate is fixed for the entire term; variable pricing can make a future payment harder to predict. Also check whether autopay discounts disappear if you cancel. Read the agreement's default and dispute provisions before treating a low quote as the safest choice.
Test the Payment Against Your Real Budget
Use a payment test based on your real budget, not a lender's maximum approval. Add the proposed payment to rent, utilities, insurance, minimum debt payments, groceries, and irregular costs such as repairs. Leave room for savings and income interruptions. If two loans fit today, stress-test them by reducing overtime, adding a medical bill, or increasing a variable expense. A payment that works only in a perfect month is a warning sign. You can also compare the loan with waiting, borrowing less, negotiating the purchase price, or using existing savings without draining your emergency reserve.
Verify the Lender Before You Apply
Before submitting an application, verify the lender and preserve your comparison notes. Check the company through your state regulator or the Consumer Financial Protection Bureau's complaint database, and avoid anyone demanding payment before explaining the loan in writing. Multiple applications can create hard inquiries, although some scoring models may treat rate-shopping for certain loans as a single event within a limited window. Ask lenders which credit check they use. Once you choose, save the agreement, payment schedule, and contact information. Revisit the decision after the first bill arrives to confirm the amount, due date, and any promised discount.
Where to continue your research safely
To keep researching, review Consumer Financial Protection Bureau personal loan guidance Consumer Financial Protection Bureau complaint database and compare which option makes the most sense for your situation.
Key criteria to compare before you decide
A good decision depends on more than a first impression. Compare total cost, timing, reputation, effort required, and the clarity of the offer conditions. When those criteria are visible together, it becomes easier to tell whether an option solves the problem or only looks attractive at first.
How to use this guide for your next step
Review the criteria before moving forward
How can you compare personal loan offers without focusing only on the monthly payment calls for context, comparison, and patience. Use the points above as a practical checklist: revisit your goal, look for concrete signals, and move forward only when the choice fits your current needs.