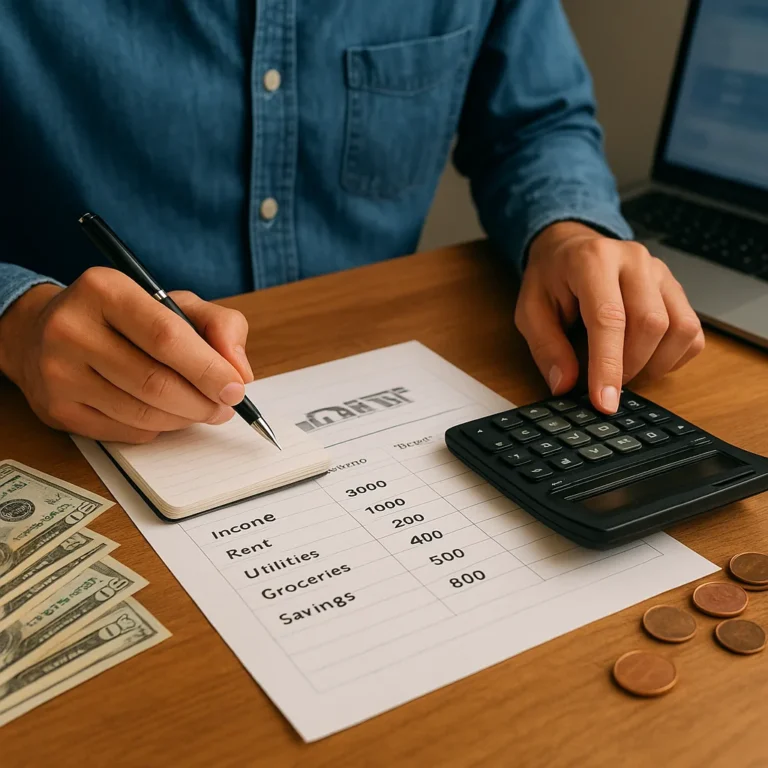
A realistic monthly budget starts with what actually reaches your bank account, not an optimistic salary figure or a perfect month you rarely experience. The goal is not to restrict every purchase; it is to give each dollar a clear job while leaving room for irregular costs, small pleasures, and changing circumstances. Start by studying your recent transactions, separating dependable income from occasional money, and identifying expenses that happen quarterly or annually. Then build a plan you can review without judgment. This guide explains how to turn real numbers into spending limits, savings targets, and practical adjustments that can survive a busy month, a higher utility bill, or an unexpected repair.
Start With Income You Can Actually Count On
Begin with a month of evidence. Download two or three months of checking and credit card statements, then list every source of take-home income and every recurring bill. Use net income, because taxes and deductions have already been removed. If your pay changes, calculate a conservative monthly baseline from your lower-earning months rather than budgeting from your best paycheck. Include predictable nonmonthly income only when it is genuinely reliable. For example, a freelancer might use the average of the three leanest recent months. This approach creates a budget grounded in cash you can reasonably expect, not money that may arrive later.
Separate Fixed, Flexible, and Irregular Costs
Separate fixed, flexible, and irregular costs before assigning limits. Fixed expenses, such as rent, insurance, and minimum debt payments, usually change little in the short term. Flexible costs include groceries, fuel, dining, and entertainment; they can move up or down. Irregular expenses are easy to miss: car registration, school supplies, annual subscriptions, medical copays, or holiday travel. Add the yearly estimate for each irregular item and divide it by twelve. A $600 annual insurance premium becomes a $50 monthly planning amount. Keeping that money in a sinking fund prevents an ordinary due date from becoming a financial emergency.
Give Your Priorities Specific Dollar Amounts
Turn priorities into categories that guide decisions, not vague hopes. After essentials and minimum obligations are covered, choose specific targets for emergency savings, retirement, extra debt payments, or a near-term purchase. Give each target a dollar amount and a date. If you want a $1,200 emergency cushion in twelve months, the initial target is $100 per month; adjust it after testing the plan. Keep categories simple enough to use consistently, but detailed enough to reveal tradeoffs. ‘Food’ may be sufficient for one household, while another may benefit from separating groceries, work lunches, and takeout.
Test the Plan Against Your Real Behavior
Test the budget against real behavior for two to four weeks before making dramatic cuts. Track purchases as they happen, including cash, delivery fees, and small recurring charges. When a category runs over, do not label the entire plan a failure. Ask whether the limit was unrealistic, the expense was one-time, or another category can absorb the difference. A weekly checkpoint makes corrections manageable: compare planned and actual spending, then move remaining money where it matters most. Automating transfers after payday can protect savings, while a small discretionary category reduces the temptation to abandon the budget entirely.
Adjust the Budget When Life Changes
Revisit your budget whenever your life changes, not only when you feel behind. A raise, new commute, roommate, medical bill, or loan payoff can change the right allocation. Keep a short note beside each adjustment so you know why the number changed and whether it worked. If expenses exceed income, focus first on timing, essential costs, subscriptions, and high-interest debt rather than cutting necessities blindly. A workable budget is allowed to evolve. Its strongest sign of success is not a perfect month; it is knowing what happened, making a measured correction, and continuing to direct money toward stability and the priorities you chose.
Where to continue your research safely
To keep researching, review Consumer Financial Protection Bureau budgeting tools and compare which option makes the most sense for your situation.
Key criteria to compare before you decide
A good decision depends on more than a first impression. Compare total cost, timing, reputation, effort required, and the clarity of the offer conditions. When those criteria are visible together, it becomes easier to tell whether an option solves the problem or only looks attractive at first.
How to use this guide for your next step
Review the criteria before moving forward
How can you build a monthly budget that reflects your actual income and expenses calls for context, comparison, and patience. Use the points above as a practical checklist: revisit your goal, look for concrete signals, and move forward only when the choice fits your current needs.